How to Calculate Landed Cost When Importing Products
A supplier's unit price is only the starting point for an import decision. The real cost of an imported product includes transportation, insurance, border charges, customs clearance and the expenses required to deliver the goods to the intended destination. Buyers who compare quotations without these additions can choose the apparently cheaper supplier and still pay more per usable unit.
Calculating landed cost before issuing a purchase order helps importers set realistic resale prices, compare manufacturers on equal terms and decide whether a shipment is economically viable. The calculation should use the destination country's actual tariff rules and a clearly defined delivery point.
What Is Included in Landed Cost?
Landed cost generally starts with the cost of the goods and adds the costs incurred to bring them to the selected destination. Depending on the transaction, these may include origin handling, international freight, cargo insurance, destination terminal charges, customs brokerage, import duties, inspection fees and domestic transportation. Include unloading, warehousing or other receiving charges if the chosen costing boundary extends to the buyer's warehouse.
Some costs are not simply expenses to add permanently. Recoverable import VAT or GST may create a cash-flow requirement without becoming a final product cost. Whether tax is recoverable depends on local law and the importer's status. Record it separately until its treatment is confirmed.
Build a Cost Worksheet
- Product price, currency and order quantity
- Incoterm and precisely named delivery place
- Origin transport and export-related charges, where payable by the buyer
- International transport and applicable insurance
- Destination handling, customs clearance and local delivery
- Applicable import duty, other nonrecoverable taxes and fees
- Currency conversion, bank fees and a realistic contingency allowance
How Incoterms Change the Calculation
Different Incoterms divide costs and responsibilities between buyer and seller. Under EXW, the buyer may face extensive collection, origin logistics and export arrangements, and the arrangement may be impractical for some cross-border transactions. Under FCA, the seller delivers to the agreed carrier or place and ordinarily handles export clearance. Under FOB, a term intended for sea and inland-waterway transport, the seller delivers the goods on board the vessel at the named loading port.
CIF includes contracted cost, insurance and freight to the named destination port, but it does not mean the buyer has no import duties or destination expenses. DAP generally takes the seller's transport responsibility to the named destination, while import clearance and duties normally remain with the buyer. DDP shifts import-clearance and duty responsibilities to the seller, where legally feasible. Always specify the Incoterms 2020 rule and named place, rather than relying on a three-letter abbreviation alone.
For a deeper comparison of destination responsibilities, see DDP vs DAP: Which Is Better for International Buyers?. For containerized cargo, ask the forwarder which terms and handover points fit the shipment.
Worked Example: Calculating Cost per Imported Unit
Suppose an importer buys 1,000 units at $8 each. The purchase price is $8,000. The buyer then expects $300 in origin charges not already covered by the seller's quotation, $1,200 in international freight, $100 in insurance, $250 in destination charges, $150 in brokerage and $400 in inland delivery. For illustration only, assume the applicable import duty is $600 and no other nonrecoverable taxes or fees apply.
Total landed cost = $8,000 + $300 + $1,200 + $100 + $250 + $150 + $400 + $600 = $11,000. Dividing by 1,000 units gives $11 per unit, compared with the quoted purchase price of $8. The example's $600 duty is an assumption, not a tariff calculation; real duty depends on classification, customs value, origin and destination rules.
If 20 units are damaged and cannot be sold, the effective cost per 980 usable units rises to approximately $11.22. This distinction matters when comparing quality, packaging and suppliers offering different shipment reliability. The total is an illustrative costing model rather than a tax or customs declaration.
How to Estimate Freight and Destination Charges
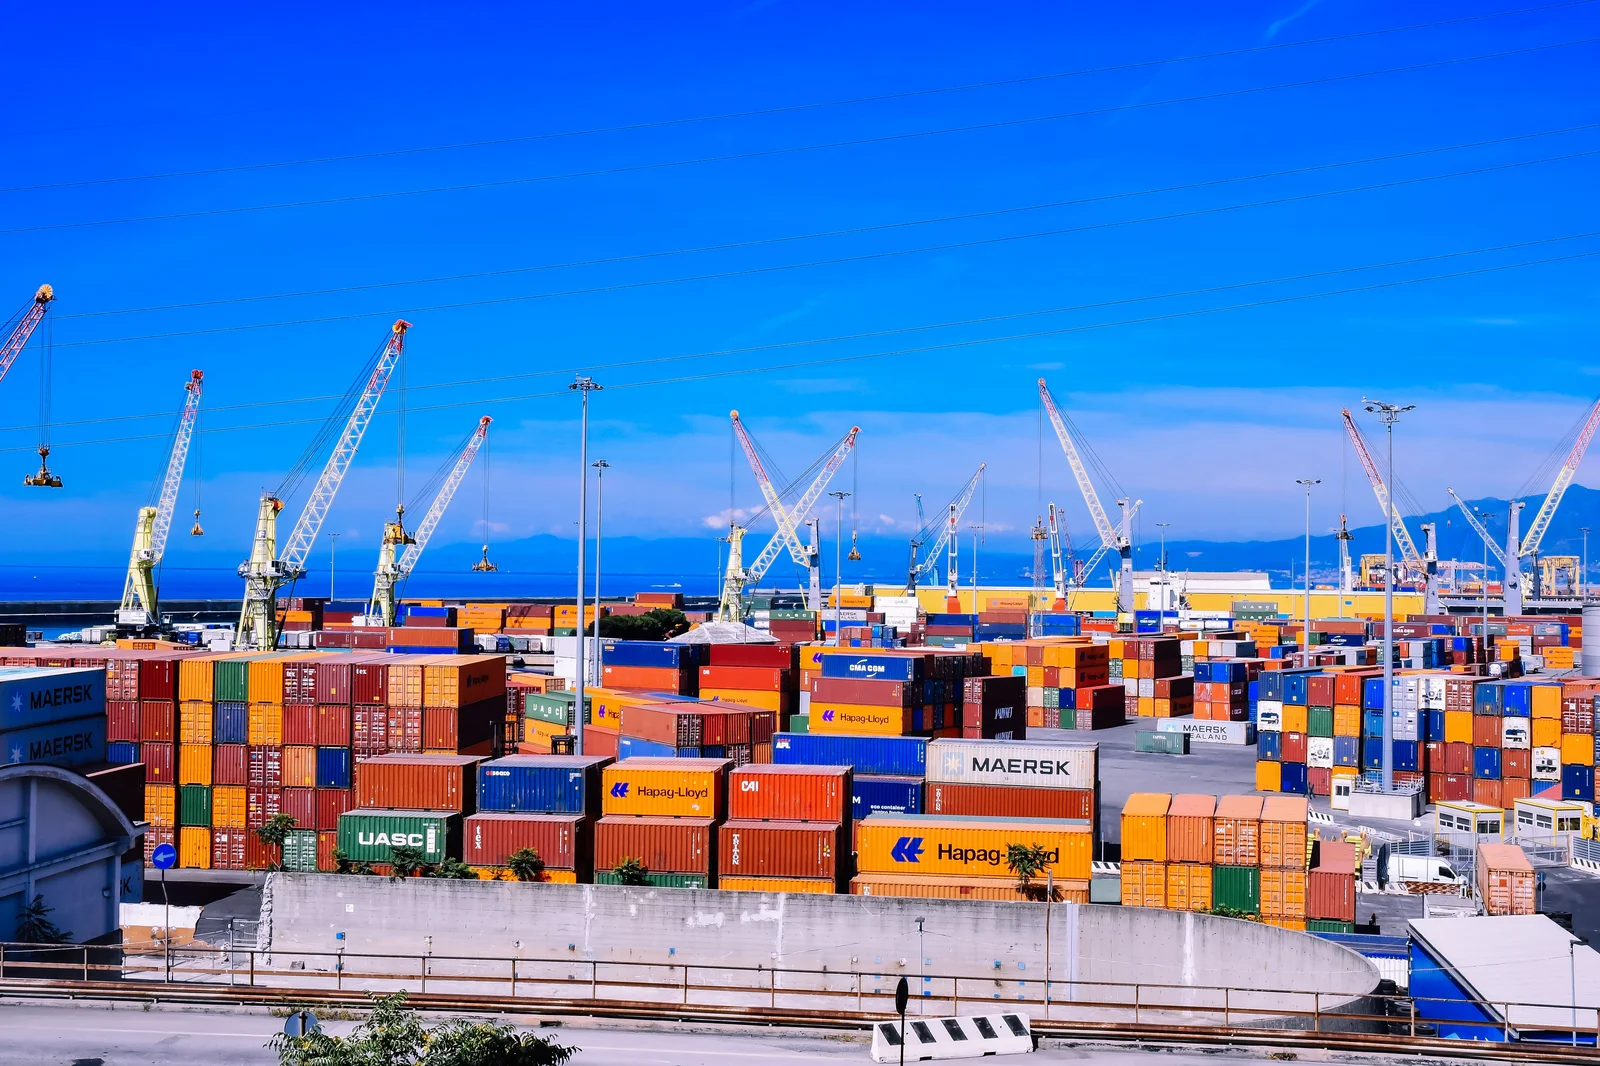
Obtain freight quotations for the actual shipment dimensions, gross weight, collection location, destination and required service. Ask which surcharges are included, how long the quote is valid and whether the freight company assumes a full-container, less-than-container or air-cargo movement. Port handling, storage, demurrage and detention can change the final amount substantially when documents or cargo are delayed.
A quotation described as “freight included” may still leave import clearance, terminal handling, delivery appointments, unloading or inland trucking outside the price. Request a written breakdown with the payer for each line. Compare carriers and suppliers using the same final delivery address and planned arrival window.
The transport mode also changes the economics: urgent, high-value shipments may justify air freight, while bulky or lower-value cargo often favors ocean transport. Consider the trade-offs in Air Freight vs Sea Freight: When Does Each Make Sense? alongside inventory carrying costs and expected lead time.
Customs Value, Classification and Tax Treatment
Duty is not necessarily calculated on the commercial invoice total alone. Customs valuation rules can require specified transport, insurance, assists, royalties or other adjustments, and these rules vary by jurisdiction. Confirm the commodity's classification and applicable duty rate with a qualified customs broker or the destination country's tariff database. Preferential duty treatment may require proof of origin and compliance with the relevant trade agreement.
Do not treat import VAT, sales tax, anti-dumping measures and customs duty as interchangeable. Some are nonrecoverable costs, some may be recoverable subject to conditions and some may apply only to particular goods or origins. Keep an auditable worksheet that distinguishes total cash needed at clearance from the long-term cost recorded per unit.
Compare Suppliers Using the Same Cost Boundary
A low EXW quote can become expensive once inland collection and export handling are added. A higher FCA or DAP quote may simplify operations and reduce uncertainty, but only a line-by-line comparison shows whether it is competitive. Request equivalent product specifications, packaging standards, inspection arrangements, payment conditions and delivery locations before comparing final unit costs.
Include anticipated defect rates, replacement arrangements and quantity discrepancies in the commercial evaluation. A supplier offering robust export packaging and reliable documentation may protect more value than a small discount on the invoice. Where quality risk is material, consider When Should You Request a Pre-Shipment Inspection? before releasing the final payment.
How Currency and Order Size Affect Unit Economics
When a supplier quotes in a foreign currency, model the exchange rate at the expected payment date, not only at the quotation date. Bank charges and foreign-exchange spreads can reduce the expected margin. It may help to calculate a base case and a less favorable currency scenario before setting a resale price.
Freight and clearance charges often include fixed components, so importing more units may lower cost per unit. Larger orders also increase tied-up cash, storage requirements and exposure to unsold stock. Compare several realistic order sizes instead of assuming the largest shipment is always the most profitable.
Final Landed Cost Checklist
- Confirm exact product specification, quantity, price and currency.
- Record the named Incoterm, location and freight payer.
- Check HS classification, country of origin and destination duty rules.
- Separate recoverable taxes from nonrecoverable costs.
- Get itemized origin, international and destination logistics quotations.
- Include customs brokerage, inspection, storage and last-mile transport as applicable.
- Allow for damaged or unsellable units and realistic exchange-rate variation.
- Calculate total cost, cost per received unit and cost per sellable unit.
A useful landed cost calculation is one that can be reconciled against actual invoices after arrival. Update your model with each shipment so future sourcing decisions rely on observed charges rather than optimistic estimates.